
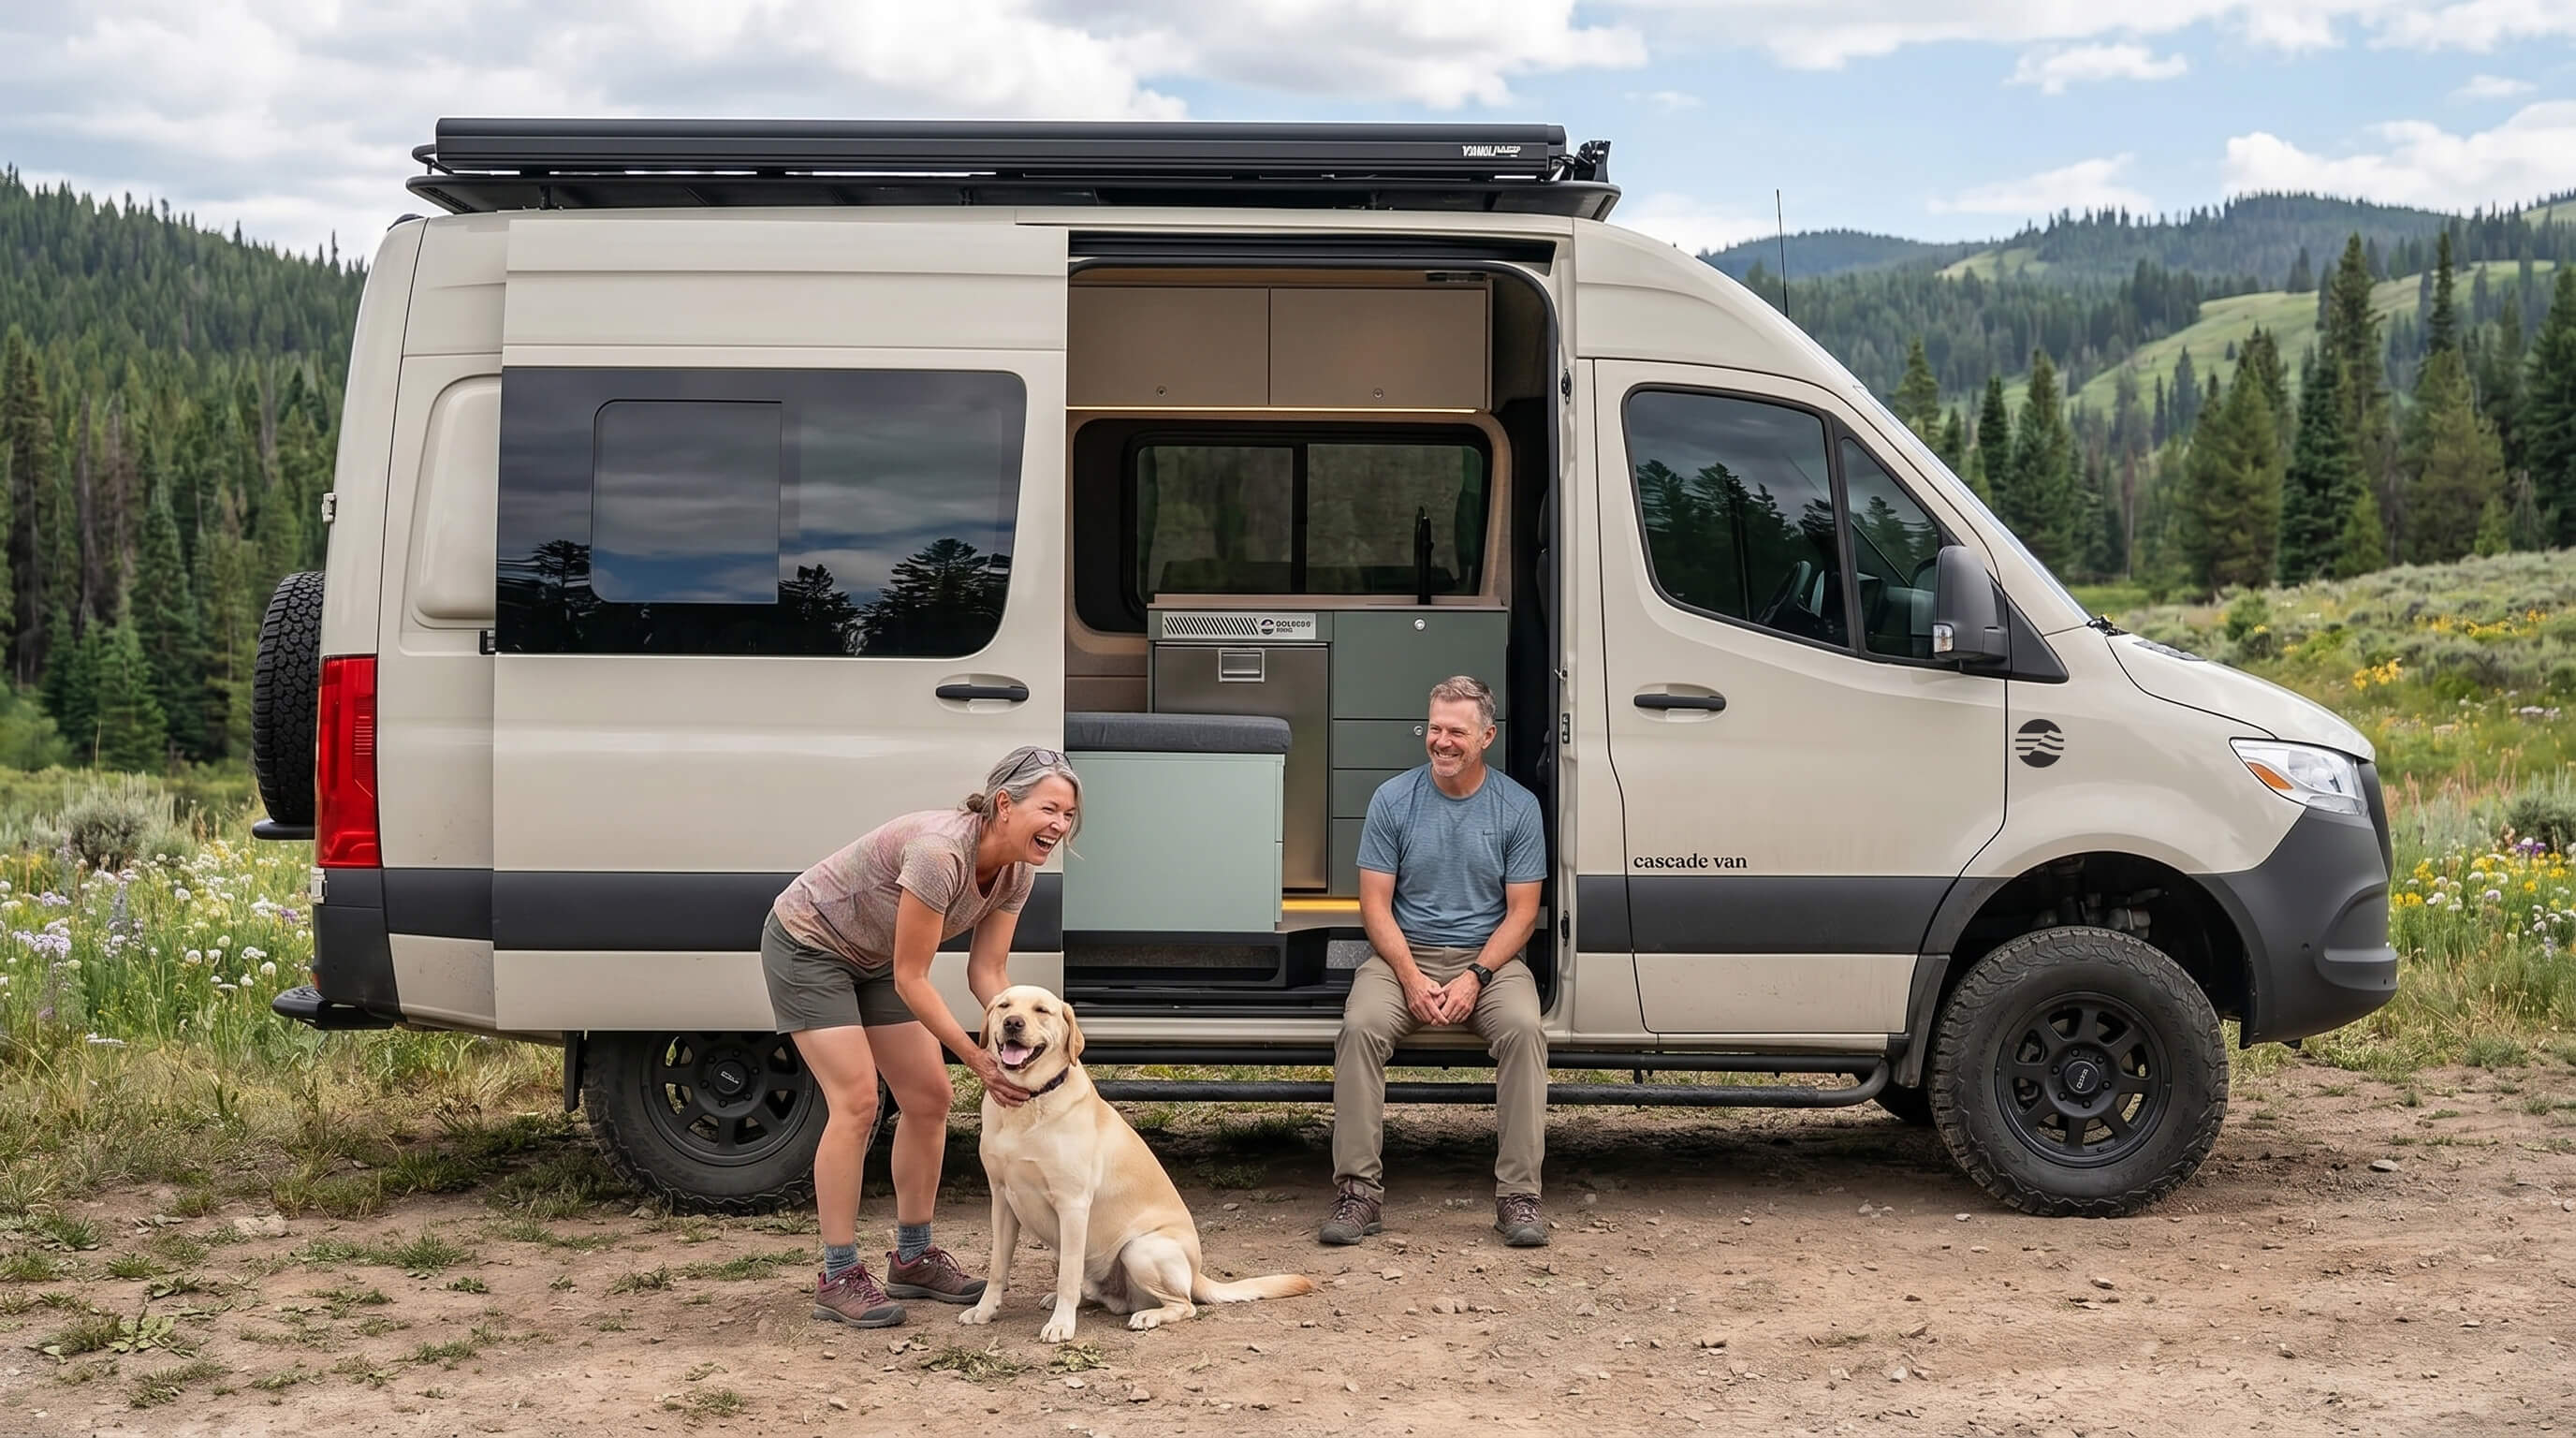
Your dream van is closer than you think
Financing your build
Experience the freedom to hit the open road with confidence, knowing that your dream campervan is within reach thanks to flexible financing options tailored to your needs. Let us help you turn your vision into reality and set forth on unforgettable journeys with ease and peace of mind. Start your adventure today!
Have questions?
For more information about financing, our build process, or getting started with your conversion, please get in touch.
Questions about financing?
We're here to help you navigate the process. Can't find the answer you're looking for? Contact us.
Can I finance a custom camper van conversion?
Yes. Most Cascade Van owners finance their build with an RV loan, a secured loan designed for recreational vehicles. Because every Cascade Van is RVIA-certified and fully documented, our vans are built to qualify for traditional RV financing, and we're happy to connect you with lenders who know our work and have financed our builds before.
What is an RV loan and how is it different from a personal loan?
An RV loan uses the van itself as collateral, similar to an auto loan. That usually means longer terms (often 10 to 20 years) and lower rates than an unsecured personal loan, which keeps monthly payments manageable on a six-figure build.
Personal loans can work for small projects, but for a full Sprinter conversion an RV loan is almost always the better tool.
Why does RVIA certification matter for financing and insurance?
Many lenders treat RVIA certification as proof that a custom conversion meets a recognized industry standard. Some require it for larger loans on custom builds, and without it you may be declined or offered a lower loan amount.
It matters for insurance too: many RV insurers require or strongly prefer RVIA certification to cover the full value of the conversion, not just the base Sprinter. Every Cascade Van is RVIA-certified.
What credit score do I need to finance a camper van?
Most RV lenders look for a credit score of 660 or higher, and scores above 720 typically qualify for noticeably better rates. Lenders also review your debt-to-income ratio, generally preferring total monthly debt (including the new payment) below about 40 to 45 percent of gross monthly income. Every lender sets its own criteria.
How much of a down payment do I need for an RV loan?
Down payment requirements vary by lender, typically 10 to 20 percent of the purchase price. Having 15 to 20 percent ready keeps you competitive with most lenders and lowers your monthly payment. Try different amounts in the financing calculator on this page to see how it affects your estimate.
What documents do I need to apply for a camper van loan?
Lenders will generally ask for:
- Proof of income (pay stubs, W-2s, or two years of tax returns if you're self-employed)
- A government-issued ID
- Your build contract or invoice detailing the conversion
- RVIA certification documentation (we provide this)
- Vehicle information such as the VIN, year, make and model
- Bank statements verifying your down payment
- An insurance binder, for some lenders
Can I finance a van that hasn't been built yet?
Yes. Some lenders fund custom builds in stages as the work progresses, while others fund the full amount once the van is complete. Ask your lender up front how they handle build-to-order vans so it lines up with our payment schedule: the deposit at contract signing, 50% at your final design meeting, and the balance two weeks before pickup.
Should I finance the Sprinter and the conversion separately?
It depends on your situation. Some owners buy or finance the base Sprinter on its own and finance the conversion separately. Many prefer a single loan on the completed, certified van, which is simpler to manage, and the appraised value of a finished RVIA-certified conversion can support a higher loan amount than the base vehicle alone.
Should I get pre-qualified before starting my build?
We recommend it. Pre-qualifying with a few lenders is usually a soft credit check, and it shows you what you can comfortably afford before you commit to a layout and options. Compare three or four offers, then use your pre-qualified amount to plan your build with us.
Can I finance a Cascade Van that's already built and for sale?
Yes. Completed vans for sale can typically be financed with an RV loan just like a custom build, and because they're RVIA-certified with full build documentation, the lending process is straightforward. Reach out and we can point you to lenders familiar with our vans.
Do I need special insurance for a converted camper van?
Yes. Standard auto insurance typically covers the base vehicle but excludes or limits coverage on the conversion itself. An RV insurance policy covers the full van, including the build-out and personal belongings. RVIA certification makes it much easier to insure a Cascade Van at its full value, and we share tips on securing RV insurance with every new owner.